Finding Notary Services at Your Local Bank
Most major retail banks and local credit unions offer notary services to the public, but availability depends heavily on the branch location and staff scheduling. The primary role of branch employees is customer banking, so while several staff members might hold active notary commissions, notarizing walk-in paperwork is usually an auxiliary service rather than their primary daily duty. In most cases, these institutions provide basic notarial certificates during standard lobby hours without charging an additional fee to their established account holders.
Whether a bank will notarize your paperwork for free typically hinges on your relationship with the institution. National banking chains and community credit unions generally provide complimentary notarizations to existing checking, savings, or commercial account holders as a courtesy benefit. If you do not hold an account with that specific bank, branch management may either charge a nominal statutory fee permitted by state law or decline the service altogether, directing you to your own financial institution or an independent mobile notary.
Before driving to your neighborhood branch, calling ahead is the most reliable way to prevent wasted time and frustration. Notary availability shifts based on employee lunch hours, staff sick days, and internal branch coverage. A quick phone call allows you to confirm that a commissioned staff member is on-site, verify whether appointments are mandatory, and ask if their branch guidelines allow them to handle your specific type of paperwork.
Situations Where Bank Branches Decline to Sign
Even when an on-duty notary is present, banks routinely refuse certain categories of legal and financial documents due to internal risk policies. Corporate compliance guidelines often bar branch employees from notarizing last wills and testaments, living trusts, real estate deeds, codicils, and complex powers of attorney. Financial institutions impose these limitations because contested estate or property documents carry substantial litigation exposure, and banks prefer to insulate their retail staff from future court subpoenas or fraud depositions.
Document readiness is another frequent reason for branch refusals. A notary public cannot complete a certificate if a document contains blank lines, missing pages, or unclear text. If the paperwork lacks standard notarial language—such as a formal jurat or certificate of acknowledgment—bank employees are legally barred from selecting the wording for you, as doing so constitutes the unauthorized practice of law. If your paperwork is incomplete or ambiguous, the branch notary must turn you away until it is corrected.
Signer verification policies at retail banks can also be surprisingly strict. The notary must be entirely confident in your identity and must evaluate your mental competency and willingness to sign without outside pressure. If an elderly relative appears confused or if a companion attempts to speak on their behalf, a bank notary will immediately decline the transaction to prevent potential undue influence or elder financial abuse allegations.
What to Prepare Before Visiting Any Branch
Arriving fully prepared makes the notarization process quick and straightforward for both you and the bank officer. The most critical requirement is bringing acceptable, unexpired government-issued photo identification. In most states, acceptable credentials include a current state driver's license, a state identification card, a United States passport, a federally recognized tribal ID, or a military identification card. If your ID has expired or the name printed on it fails to match the name on your paperwork, the notary cannot proceed.
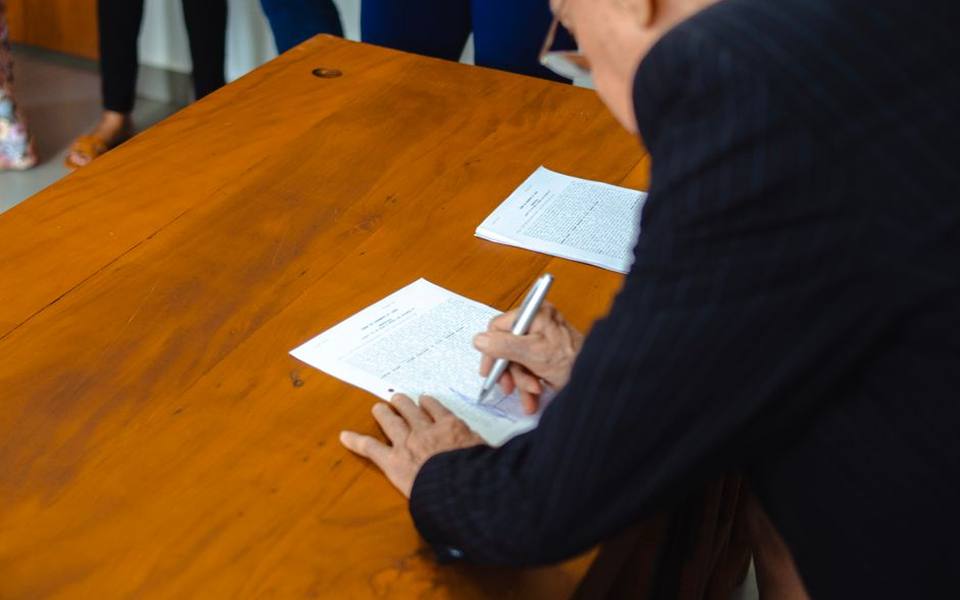
The single most common mistake signers make is signing the document before reaching the notary desk. For an acknowledgment, you must confirm to the notary that the signature is yours, but for a jurat or sworn statement, the law explicitly requires you to sign the page in the physical presence of the notary after taking a verbal oath. To avoid having your document rejected or being forced to print out a fresh copy, keep every signature line and date box completely blank until the notary tells you to sign.
If your paperwork involves multiple signers, every individual named on the document must appear in person at the same time, each carrying their own qualifying government identification. If an individual cannot make the trip due to work schedules or health limitations, the bank cannot complete that portion of the certificate. In situations where bringing all parties together at a retail branch is impractical, alternative mobile or digital signing methods offer far greater flexibility.
Where to Turn When the Bank Is Not an Option
When your bank declines your paperwork or branch operating hours conflict with your work schedule, you have several reliable alternatives. Commercial shipping outlets, packaging storefronts, and local print shops routinely keep commissioned notaries on staff during extended business hours. Municipal offices, city hall records desks, and public library systems in many counties also provide notarial services for basic administrative forms, often charging only the minimal statutory rate set by state legislation.
For complex documents or signers with limited mobility, hiring a professional mobile notary is often the most practical solution. Mobile practitioners travel directly to residences, corporate offices, nursing homes, rehabilitation facilities, or hospital bedsides to execute signatures on demand. When unexpected legal deadlines arise outside standard banking windows, verified providers like After-Hours Mobile Notaries can accommodate late evening, weekend, and holiday requests that brick-and-mortar institutions cannot handle.
Finding an independent professional who handles specialized legal or personal paperwork has become much simpler through organized regional directories. With more than 4,212 listings cataloged across high-demand states, consumers can quickly locate qualified notaries in their immediate geographic area, verify the specific services they provide, and schedule an appointment that fits their personal timetable.
Modern Convenience Through Remote Online Platforms
In recent years, remote online notarization—frequently referred to as RON—has transformed how individuals and businesses execute formal paperwork across the United States. Rather than traveling to a local retail bank or arranging an in-person meeting with a mobile professional, signers can connect with a commissioned officer through a secure, two-way audio-video internet connection using a standard computer, tablet, or smartphone.
Remote platforms verify identity using sophisticated technological safeguards that surpass traditional visual ID inspections. Signers upload high-resolution images of their government credentials, which undergo automated forensic credential analysis, followed by dynamic knowledge-based authentication questions drawn from public records and credit history databases. Once identity verification is satisfied, the parties review the document on screen, apply compliant digital signatures, and attach an electronic notarial seal.
Interstate recognition statutes allow signers located anywhere to utilize electronic notarization, provided the commissioned notary operates under the legal framework of an authorized RON state. If you live in a rural area, lack reliable transportation, or simply want to finalize an agreement without leaving your desk, connecting with certified Remote Online Notaries (RON) provides an efficient, paperless alternative to waiting in line at a local financial branch.
How Much Notarizations Typically Cost
The question of how much a notary can charge depends strictly on the laws of the state where the commission was granted. Most state governments establish mandatory fee ceilings for standard notarial acts, typically capping basic acknowledgments, jurats, and verbal oaths between two dollars and fifteen dollars per signature stamp. Some states permit slightly higher statutory fees, while a few jurisdictions prohibit charging any fee for basic notarial acts altogether.
Because retail banks and credit unions frequently absorb these minor statutory expenses as an operational perk for their clients, walking into your own branch remains one of the few avenues to secure completely free notarizations. Independent commercial storefronts, such as shipping franchises, typically charge the maximum state-regulated fee per individual notarial certificate, which can add up quickly if your packet contains multiple signature endorsements.
When you hire a mobile notary to meet you at your home, workplace, or healthcare facility, the total fee structure changes. While the fee for the actual notarial stamp remains bound by statutory state limits, mobile professionals are legally permitted to bill separate travel fees, mileage, waiting time, and convenience premiums. Mobile travel charges generally range from thirty dollars to well over one hundred dollars, depending on travel distance, time of day, and how quickly the signer needs the visit completed.
Higher Fees for Specialized Legal Paperwork
Not all notarizations involve quick one-page affidavits or vehicle title transfers. High-liability transactions, such as residential mortgage refinances, commercial property purchases, structured settlement agreements, and complex family estates, involve extensive packets that require specialized expertise and significant time commitments. For these intensive assignments, fees reflect the elevated level of responsibility, training, and logistical coordination involved.
Real estate mortgage packages frequently exceed one hundred pages and require dozens of signatures, initialed paragraphs, and formal acknowledgments. Professionals serving as designated Loan Signing Agents typically earn flat package fees rather than individual stamp rates. These assignments, paid by title agencies, escrow firms, or mortgage lenders, generally range from seventy-five dollars to two hundred dollars per completed signing appointment depending on package size and return courier requirements.
Similarly, sensitive legal authorizations demand rigorous care to prevent legal challenges later on. Qualified Power of Attorney & Legal Paperwork Notaries often handle time-sensitive healthcare proxies, financial designations, and living wills within clinical or assisted-care environments. Because these papers require meticulous identity vetting and strict verification of sound mental capacity, fees for these specialized appointments naturally exceed routine walk-in bank rates.
Earning Potential and Income for Commissioned Notaries
Many professionals and entrepreneurs look into notarization as a versatile side income stream or the foundation for a full-time mobile business. How much a commissioned notary can earn varies substantially based on geographic location, service specialization, marketing initiative, and working hours. Notaries who simply stamp documents as a secondary function of their day jobs—such as bank tellers, paralegals, or auto dealership clerks—rarely earn direct signing income, as their fees generally belong to their employers.
Independent mobile practitioners who operate as general notaries typically earn between twenty and forty dollars per routine residential appointment after deducting travel expenses. While routine notarizations provide steady supplemental cash flow, earning a robust full-time living purely on standard five-dollar stamps is difficult due to travel overhead, vehicle maintenance, and scheduling limits.
In contrast, full-time independent signing agents who establish steady referral pipelines with title companies, real estate brokerages, elder law attorneys, and local corporate firms can achieve significant annual earnings. Successful full-time signing professionals who work flexible hours, manage evening appointments, and cover rural or underserved territories can generate several thousand dollars monthly, though business income fluctuates with broader real estate market trends and interest rate cycles.
How to Obtain a Notary Public License
If you want to become a notary yourself, the commissioning process is managed at the state level, typically administered through the Secretary of State or a designated licensing division. Basic qualification standards across the country require an applicant to be at least eighteen years of age, maintain legal residency or authorized employment within the commissioning state, and possess a clean criminal record free of felony convictions or crimes involving fraud and moral turpitude.
The first practical step usually involves completing a state-approved educational course covering relevant notarial statutes, proper record-keeping, prohibited actions, and identity verification protocols. While some states do not mandate formal study hours, an increasing number require a three- to six-hour certified course followed by a proctored or online state examination designed to test your understanding of acknowledgments, jurats, and document administration.
After passing any required examination, candidates submit an official application along with state filing fees, which generally cost between twenty and one hundred dollars. In most states, applicants must also submit to state and federal background checks through electronic fingerprinting. Once the state licensing authority reviews and approves the background clearance, they issue a formal commission packet or appointment certificate.
Final Steps to Active Commissioning and Practice
Receiving your appointment letter from the state does not immediately authorize you to begin stamping documents. In nearly all jurisdictions, newly commissioned notaries must obtain a mandatory surety bond before taking their oath. A notary surety bond is a financial guarantee that protects the public—not the notary—against financial harm resulting from errors or misconduct. Bond amounts typically range from one thousand dollars to twenty-five thousand dollars, costing the applicant a modest one-time premium.
With your surety bond secured, you must file your official oath of office with the county clerk or state commissioning office, usually within thirty to sixty days of your appointment date. Failing to record your oath within this statutory window voids the commission, forcing you to restart the application process from the beginning. Many prudent practitioners also purchase Errors and Omissions (E&O) insurance at this stage to protect their personal assets against unwarranted lawsuits or inadvertent clerical mistakes.
The final phase involves purchasing your required professional tools from an authorized vendor. You will need an official rubber ink stamp or embosser manufactured to strict state dimensional guidelines, alongside a secure, bound notarial record book. Once your seal is registered and your record journal is prepared, you are legally empowered to administer oaths, verify signatures, and serve the public in accordance with state laws.
Published 2026-09-20 · reviewed with each rebuild, last September 2026.
Find notaries near you
The directory lists 5,516 notaries by state and city — pick your state or use the “Near me” button in the header.
More guides
-
 Service
A Practical Guide to Power of Attorney: What It Means, Typical Costs, and Proper Execution
-
 Service
Where and How to Get Fingerprinted for an FBI Background Check
-
 Owning
Understanding Real Estate Deeds: Transfer on Death, Deed of Trust, and Mortgages
-
 Service
What Is an Apostille? How to Get Birth Certificates and Documents Apostilled
-
 Owning
Essential Legal Documents: Bills of Sale, Estate Affidavits, and Corporate Records
-
 Money
How Much Does a Notary Cost? Standard Fees, Travel Rates, and Extra Charges Explained
-
 Owning
Which Documents Need to Be Notarized? Leases, Notes, and Directives Explained
-
 Buying
Complete Bill of Sale Guide: Vehicle, Boat, and General Templates
-
 Service
Form I-9 Employment Eligibility Verification: Acceptable Documents and Rules
-
 Service
LLC Formation Documents, Residence Proof Affidavits, and Legal Verification
-
 Owning
How to Become a Notary Public: Supplies, Stamps, Training, and E&O Insurance
-
 Service
Fingerprinting and Live Scan Background Checks: Methods, Locations, and Cards
-
 Service
A Consumer Guide to Notary Public Services and Remote Online Notarization
-
 Service
Estate Planning Essentials: Wills, Codicils, and Healthcare Power of Attorney
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
Live Scan Fingerprinting and FBI Background Check Services Guide
-
 Service
Form I-9 Employment Verification and Identity Proofing Guide
-
 Service
Notary Training, Commissioning, Bonding, and E&O Insurance Guide
-
 Owning
A Complete Guide to Power of Attorney: Types, Forms, and Execution
-
 Money
Home Refinance and Cash-Out Mortgage Guide: Loan Closing, Rates, and Calculations
-
 Buying
Vehicle Title Transfer and Bill of Sale Guide: DMV Process, Forms, and Notarization
-
 Owning
Estate Planning and Real Estate Document Guide: Wills, Deeds, and Affidavits
-
 Owning
Articles of Incorporation and Corporate Filing Guide: LLCs, Nonprofits, and Bylaws
-
 Buying
Essential Notary Supplies Guide: Stamps, Embossing Seals, Journals, and Scanners
-
 Service
Remote Online Notarization and Mobile Notary Services Guide: How It Works and Costs
-
 Safety
Minor Travel Consent and Passport Documentation Guide: Forms, Rules, and Notarization
-
 Service
International Document Apostille, USCIS Translation, and Legalization Guide
-
 Money
Property Tax Appeal and Protest Guide: Process, Filing Forms, and Representation
-
 Buying
Motor Vehicle Bills of Sale and Title Transfers: A Complete Guide
-
 Money
A Practical Guide to 401(k) Hardship Withdrawals and Emergency Access
-
 Owning
Heavy-Duty Fasteners, Scanners, and Document Handling Equipment for Notaries
-
 Service
Live Scan Fingerprinting, Background Checks, and Identity Verification: A Complete Practical Guide
-
 Service
Notary Public Training, Essential Supplies, and Digital Workflow Guide
-
 Owning
Corporate Formation and Governance: Articles of Incorporation and Board Minutes
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
A Practical Guide to Affidavits, Proof of Residency, and Identity Declarations
-
 Money
Mortgage Cash-Out Refinancing: Equity Rules, Liens, and Closing Procedures
-
 Service
Certified Translation Services and State Department Legalization
-
 Service
A Practical Guide to Fingerprinting Services, LiveScan, and Identity Verification