The Fundamental Building Blocks of an Estate Plan
A complete estate plan does far more than decide who inherits property after someone passes away. At its core, an estate plan creates a practical framework that protects your legal rights, your personal medical preferences, and your financial security both during your lifetime and after death. Many people postpone creating these records because the legal terminology feels intimidating, but the primary structure relies on only a handful of distinct, purposeful legal instruments that work alongside each other.
The centerpiece for distributing possessions is traditionally known as a last will and testament, sometimes colloquially searched or referred to as a final will. While this document speaks only after death, everyday life requires instruments that function while you are still alive. Sudden accidents or critical illnesses can leave an individual unable to voice decisions, which is why instruments that appoint trusted advocates for personal welfare and asset management are equally critical.
Navigating this process begins with understanding how documents divide responsibilities. By matching each legal form to its specific purpose—whether managing bank accounts, dictating hospital treatment, or distributing real property—you avoid legal ambiguity. Coordinating these instruments properly ensures your relatives are not left guessing your intentions or forced into lengthy, expensive probate court disputes during an already stressful family crisis.
Understanding the Role of a Last Will and Testament
A last will serves as the formal declaration of how you want your personal estate distributed once you pass away. Although casual conversation often introduces slight variations like a last willing testament or simple final testament, the legal mechanism remains uniform. In this instrument, you identify your beneficiaries, specify who receives particular family heirlooms or real estate, and nominate an executor who will administer the estate according to your specific instructions under local court supervision.
Beyond property distribution, a will provides parents of minor children with an indispensable tool: the legal designation of a guardian. If parents pass away unexpectedly without naming a guardian, a family court judge must decide who raises the surviving children, often relying on formal statutory defaults rather than personal family dynamics. Establishing your preference directly inside a properly executed will gives the probate court clear evidence of what you felt was safest for your household.
To become legally binding, a will must comply with strict state-level execution formalities. In most jurisdictions, the person creating the will—known as the testator—must sign the final document in the physical presence of two adult witnesses who hold no financial stake in the outcome. While some jurisdictions allow handwritten provisions under very narrow conditions, preparing a clean, typed document avoids the substantial probate challenges that frequently derail informal or incomplete records.
Making Minor Changes Through a Legal Codicil
Life circumstances inevitably shift over time, whether through the birth of a child, the loss of an appointed executor, or the sale of an asset mentioned in your original paperwork. When you need to modify an existing will without completely rewriting every clause from scratch, an amendment known as a codicil can be drafted. This secondary document references the original will, specifies the exact paragraphs being added, amended, or revoked, and confirms that the remainder of the original text stays intact.
A codicil must be executed with the exact same statutory formalities as the primary will itself. That means you cannot simply write notes in the margins of your existing pages, cross out paragraphs with a pen, or tape new instructions onto the paper. In the eyes of a probate judge, defacing an existing signed document can inadvertently trigger questions of revocation, potentially invalidating the entire will. Instead, drafting a formal codicil ensures legal continuity while preserving your updated preferences.
While codicils offer a practical fix for isolated adjustments—such as replacing an alternate executor or modifying a specific cash gift—they are not always the best path forward. If you find yourself making multiple updates over several years, having separate amendments can lead to confusion, conflicting interpretations, or misplaced attachments during probate. In scenarios involving major structural revisions, executing a completely new will that explicitly revokes all prior instruments is generally the safer route.
Appointing an Agent for Healthcare Decisions
Medical emergencies can occur suddenly, leaving an individual temporarily or permanently incapacitated and unable to communicate with clinical staff. In these moments, medical personnel require clear authorization regarding who holds the legal authority to make clinical choices. A health care proxy, frequently referred to as a health poa or medical power of attorney, establishes this crucial agency by designating a representative to speak directly with doctors on your behalf.
Completing your medical poa paperwork allows you to specify how treatments should be handled if you cannot communicate directly. Depending on the state, this role may be paired with a living will, creating a broader advance healthcare directive. Your chosen surrogate can access medical records under privacy regulations, consent to or refuse proposed surgical operations, evaluate diagnostic plans, and enforce your personal preferences regarding life-sustaining treatment, pain management, and palliative care.
Selecting the right person for this role requires careful thought. Your healthcare agent does not need to be a medical professional, but they must be someone capable of making difficult decisions under emotional pressure and willing to honor your stated values even if other family members disagree. Having transparent discussions with your chosen surrogate well before submitting the paperwork helps ensure they understand your baseline comfort levels regarding prolonged medical interventions.
Distinguishing Healthcare Directives from Financial Powers of Attorney
A frequent point of confusion among families involves the practical boundaries between medical authorizations and financial management forms. Laypersons sometimes search for what they mistakenly call a durable power of lawyer, confusing the legal profession with an attorney-in-fact. In American law, a durable power of attorney does not hire an attorney-at-law; rather, it appoints a private representative—known as your agent or attorney-in-fact—to manage personal, commercial, and financial transactions if you become incapacitated.
A standard healthcare directive grants authority solely over medical decisions and physical well-being. It does not empower your medical agent to pay your monthly mortgage, manage your investment accounts, file your tax returns, or handle business operations. To secure those practical matters, a separate durable financial instrument is mandatory. The term durable is significant because it indicates that the authority granted to your agent survives and remains fully operational even if you lose mental capacity.
Using comprehensive power of attorney notarization ensures that banks, title companies, and financial institutions will recognize your agent's legal standing when urgent action is required. Without a valid durable financial instrument in place, family members may be forced to file for a court-ordered conservatorship or guardianship simply to access bank funds to pay for ongoing care, leading to unnecessary delays and thousands of dollars in legal expenses.
Understanding Witness and Notarization Rules
Executing estate planning records requires precise adherence to statutory rules that vary by jurisdiction. In most states, a will requires the signatures of at least two disinterested witnesses—individuals who will receive no financial benefit or legacy under the terms of the document. Although some states do not strictly require a notary public for the will itself to be valid, standard practice involves attaching a notarized self-proving affidavit to eliminate the need for witnesses to testify in probate court later.
A self-proving affidavit is signed by the testator and the witnesses under oath before a licensed notary public. This notarized statement attests that the testator appeared of sound mind, understood the nature of the transaction, and signed freely without coercion or undue influence. Connecting with an experienced professional through a notary for legal paperwork helps confirm that each party presents verified identification and that all jurat or acknowledgment certificates align with local statutes.
Healthcare proxies and durable financial instruments carry their own specific signing prerequisites. Certain states demand two qualified witnesses, others demand an acknowledgment before a notary public, and several permit either option. Because healthcare and banking institutions regularly inspect these records for potential irregularities, completing both witness signatures and formal notarization offers the highest level of institutional acceptance across different states.
Navigating Urgent Signings and Remote Options
Life does not always afford the luxury of scheduling legal appointments during standard business hours. Critical medical diagnoses, sudden cognitive decline, or impending surgeries frequently require individuals to finalize their estate documents on an urgent timeline. When dealing with hospitalized patients or individuals with limited mobility, arranging for traditional office visits becomes impractical or entirely impossible, creating heightened logistical stress for families.
In these pressing circumstances, working with after-hours mobile notaries can provide the required flexibility. Mobile signing professionals travel directly to hospital rooms, hospice facilities, assisted living communities, or private residences during evenings and weekends. Their presence helps ensure that vulnerable signers are properly identified, evaluated for basic mental clarity and voluntary consent, and guided through the signing process in full compliance with state rules.
For signers who cannot coordinate an in-person meeting or whose witnesses reside in different cities, modern statutes in many jurisdictions now permit remote online notarization. This process utilizes secure audiovisual technology and multi-layered identity verification to execute documents digitally. However, because state acceptance for electronically signed wills remains fragmented, it is essential to verify whether your specific jurisdiction and local probate court recognize digital estate records before proceeding.
Critical Mistakes That Invalidate Estate Documents
Even carefully considered plans can fail if the underlying documentation contains execution errors. One of the most widespread missteps is using interested witnesses—such as a spouse, adult child, or named heir—to witness a will or codicil. Under state probate laws, an interested witness can be legally disqualified from receiving their designated inheritance, or their presence can cast doubt on the validity of the entire instrument during probate hearings.
Another significant pitfall is failing to address document consistency. If a newly created codicil uses vague phrasing that conflicts with unrevoked clauses in an older will, probate administrators must attempt to reconcile the contradictions. Similar friction arises when individuals complete multiple healthcare forms over several hospital visits, accidentally naming conflicting healthcare proxies without revoking previous selections, leaving medical staff unsure who holds final legal authority.
Improper storage of original signed records represents another frequent point of failure. Unlike photocopies of business agreements, probate courts generally require the original physical document with wet-ink signatures to prove a will. If an original will is lost, damaged, or held in an inaccessible location, state law may apply a legal presumption that the testator intentionally destroyed and revoked it, forcing the estate into default statutory administration.
Proper Storage and Distribution of Completed Records
Once your documents are signed, witnessed, and notarized, safe storage becomes your next priority. Many people assume a bank safe deposit box is the ideal spot, but this can create an unexpected barrier. In many states, banks freeze safe deposit boxes upon the owner's death until an executor obtains court authorization—which the executor cannot easily secure without the original will locked inside the box.
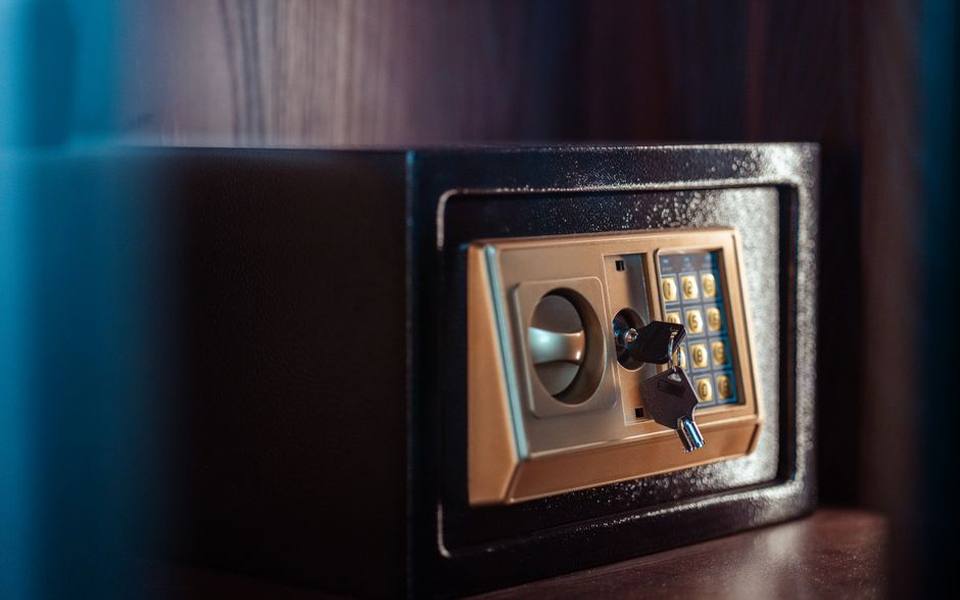
A practical alternative is storing originals in a high-quality fireproof and waterproof home safe, ensuring that your designated executor or alternate agent knows the combination or where the key is kept. Alternatively, some county probate courts offer a voluntary wills repository where testators can deposit original wills for safekeeping during their lifetime for a nominal administrative fee.
Unlike a will—which remains private until death—your healthcare directives and durable financial forms should be actively distributed. Provide a complete copy of your healthcare proxy to your primary care physician to enter into your medical record, and share copies with your chosen agent. For durable financial instruments, your appointed agent should keep a certified copy readily accessible so they can act immediately if an unexpected emergency occurs.
Keeping Your Estate Plan Current Across Life Transitions
An estate plan is not a static instrument meant to be filed away and forgotten permanently. Major life transitions—such as marriage, divorce, relocation to another state, or the passing of an executor—warrant a fresh review of your paperwork. Relocating across state lines is especially significant because probate processes, marital property classifications, and statutory power of attorney language can vary substantially between different jurisdictions.
A standard rule of thumb among legal professionals is to review your estate portfolio every three to five years, or immediately following any significant personal milestone. If your chosen healthcare agent relocates overseas or develops health issues of their own, designating a successor ensures you are never left without representation. Similarly, tax codes and estate exemption thresholds shift periodically, making regular evaluations a sensible financial habit.
When updates are needed, locating credentialed signing agents through a national notary directory simplifies the execution phase. Whether you need a simple codicil formalized, an updated medical proxy executed, or comprehensive estate documents notarized, taking deliberate, proactive steps guarantees your estate plan accurately reflects your current relationships, assets, and personal values.
Published 2026-09-20 · reviewed with each rebuild, last September 2026.
Find notaries near you
The directory lists 5,516 notaries by state and city — pick your state or use the “Near me” button in the header.
More guides
-
 Service
A Practical Guide to Power of Attorney: What It Means, Typical Costs, and Proper Execution
-
 Service
Where and How to Get Fingerprinted for an FBI Background Check
-
 Owning
Understanding Real Estate Deeds: Transfer on Death, Deed of Trust, and Mortgages
-
 Service
What Is an Apostille? How to Get Birth Certificates and Documents Apostilled
-
 Service
Do Banks Notarize Documents? Free Branch Options, Notary Fees, and Licensing Guide
-
 Owning
Essential Legal Documents: Bills of Sale, Estate Affidavits, and Corporate Records
-
 Money
How Much Does a Notary Cost? Standard Fees, Travel Rates, and Extra Charges Explained
-
 Owning
Which Documents Need to Be Notarized? Leases, Notes, and Directives Explained
-
 Buying
Complete Bill of Sale Guide: Vehicle, Boat, and General Templates
-
 Service
Form I-9 Employment Eligibility Verification: Acceptable Documents and Rules
-
 Service
LLC Formation Documents, Residence Proof Affidavits, and Legal Verification
-
 Owning
How to Become a Notary Public: Supplies, Stamps, Training, and E&O Insurance
-
 Service
Fingerprinting and Live Scan Background Checks: Methods, Locations, and Cards
-
 Service
A Consumer Guide to Notary Public Services and Remote Online Notarization
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
Live Scan Fingerprinting and FBI Background Check Services Guide
-
 Service
Form I-9 Employment Verification and Identity Proofing Guide
-
 Service
Notary Training, Commissioning, Bonding, and E&O Insurance Guide
-
 Owning
A Complete Guide to Power of Attorney: Types, Forms, and Execution
-
 Money
Home Refinance and Cash-Out Mortgage Guide: Loan Closing, Rates, and Calculations
-
 Buying
Vehicle Title Transfer and Bill of Sale Guide: DMV Process, Forms, and Notarization
-
 Owning
Estate Planning and Real Estate Document Guide: Wills, Deeds, and Affidavits
-
 Owning
Articles of Incorporation and Corporate Filing Guide: LLCs, Nonprofits, and Bylaws
-
 Buying
Essential Notary Supplies Guide: Stamps, Embossing Seals, Journals, and Scanners
-
 Service
Remote Online Notarization and Mobile Notary Services Guide: How It Works and Costs
-
 Safety
Minor Travel Consent and Passport Documentation Guide: Forms, Rules, and Notarization
-
 Service
International Document Apostille, USCIS Translation, and Legalization Guide
-
 Money
Property Tax Appeal and Protest Guide: Process, Filing Forms, and Representation
-
 Buying
Motor Vehicle Bills of Sale and Title Transfers: A Complete Guide
-
 Money
A Practical Guide to 401(k) Hardship Withdrawals and Emergency Access
-
 Owning
Heavy-Duty Fasteners, Scanners, and Document Handling Equipment for Notaries
-
 Service
Live Scan Fingerprinting, Background Checks, and Identity Verification: A Complete Practical Guide
-
 Service
Notary Public Training, Essential Supplies, and Digital Workflow Guide
-
 Owning
Corporate Formation and Governance: Articles of Incorporation and Board Minutes
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
A Practical Guide to Affidavits, Proof of Residency, and Identity Declarations
-
 Money
Mortgage Cash-Out Refinancing: Equity Rules, Liens, and Closing Procedures
-
 Service
Certified Translation Services and State Department Legalization
-
 Service
A Practical Guide to Fingerprinting Services, LiveScan, and Identity Verification