The Step-by-Step Path to Earning Your Commission
Becoming an official notary public starts with meeting your jurisdiction's basic statutory criteria, completing an application, and passing a background check. In most states, applicants must be at least eighteen years of age, legally reside in or maintain a primary place of business within the commissioning state, and possess a clean criminal record without felony convictions. The entire application timeline typically takes anywhere from two to eight weeks, depending on state processing speeds and local county clerk recording procedures.
The journey begins by submitting an application packet directly to your state appointing authority, which is usually the Secretary of State or a department of licensing. Along with the application form, you will generally pay a state processing fee and agree to undergo fingerprinting through a state-approved live scan vendor. The background screening verifies moral character and ensures that public signers will be protected from fraud, financial crimes, or conflicts of interest.
Once your paperwork clears administrative review, your state issues an official commission certificate. Receiving this document grants you the authority to take the oath of office, file your mandatory bond if your state requires one, and purchase your official tools. While the basic credential authorizes you to perform standard oaths, acknowledgments, and copy certifications, launching a successful mobile or remote service requires careful preparation and the right equipment.
Navigating the Mandatory Notary Training Course and Exam
State educational mandates vary widely across the United States, with several regions requiring formal coursework before you can sit for an examination. Taking a structured notary training course introduces you to the core duties of validating signer identity, assessing willing participation, and avoiding unauthorized practice of law. Even in jurisdictions where training remains voluntary, completing an approved educational program protects both the general public and your personal legal standing.
In heavily regulated jurisdictions such as notaries in California, completing an approved six-hour course of study is mandatory for new applicants, followed by a proctored state examination. In other regions, training may consist of a three-hour seminar, an interactive digital module, or simply a review of a state-published handbook. The curriculum covers foundational topics like handling non-standard identification, verifying credible witnesses, and recording document signers.
Passing your state test typically requires demonstrating competence in statutory identification rules, fees, and prohibited actions. Preparing thoroughly ensures you understand when a signature cannot be legally notarized, such as when a signer exhibits confusion or when the document contains blank spaces. Investing time in your education upfront prevents costly procedural errors that could lead to disciplinary reprimands or revoked commissions later.
Demystifying the Official Notary Public Stamp and Seal
Every commissioned official must possess an authentic notary public stamp and seal that strictly complies with state legislative design statutes. While you might occasionally hear newcomers mistakenly search for a notary republic stamp, the correct legal title is always notary public, reflecting an ancient common-law office designed to serve the general commonwealth. Your official marking acts as prima facie evidence that an authorized official verified the signer's identity and witnessed their voluntary execution of the document.
The physical layout of a notary public stamp is tightly controlled by state administrative code. Most states require a rectangular or circular border enclosing specific legal data: your commissioned name as it appears on your certificate, the state seal or phrase of authority, your commission number, the county of filing, and your commission expiration date. Using an altered, non-compliant, or blurred impression can cause recorders of deeds or foreign agencies to reject your clients' important paperwork.
Historically, the traditional notary public seal was a mechanical embosser that created a raised, colorless impression directly on parchment. While some states still permit or even encourage an embosser for international use or decorative purposes, nearly all modern jurisdictions require an inked stamp. Inked impressions produce clean, dark images that copy, photograph, and scan legibly into electronic court records and land title databases.
Choosing Between Traditional Rubber Ink Stamp and Self Inking Models
When purchasing your marking device, you will encounter distinct mechanical styles designed for different workloads and budgets. A traditional rubber ink stamp consists of a mounted rubber die on a wooden or plastic handle, requiring an external inked pad. While durable and inexpensive, using a separate ink pad increases the chance of over-inking your die, dripping ink on legal documents, or producing an uneven, blotchy imprint that obscures important text.
Modern practitioners overwhelmingly prefer self stamping stamps that house an internal mechanical chassis. In a standard self inking stamp, an internal spring-loaded mechanism keeps the die resting against a replaceable ink cartridge inside the device until you press down. As you push the housing onto the page, the rubber rotates downward, delivering a crisp, uniform impression before retracting back against the pad, making it ideal for standard administrative tasks.
For professionals who handle heavy volume on a daily basis, pre-inked stamps provide an even sharper impression without the mechanical flip motion of standard units. Pre-inked models feature micro-porous gel dies soaked with oil-based ink that release a microscopic layer upon direct surface contact. While slightly more expensive initially, pre-inked designs deliver thousands of ultra-sharp impressions without mechanical wear, making them a favored choice for full-time mobile professionals.
Maintaining Your Tools and Choosing the Right Ink for Self Inking Stamp
Maintaining your equipment ensures your official mark remains legible throughout your entire commission period. Using the wrong ink for self inking stamp mechanisms can ruin the internal pad, melt synthetic rubber dies, or produce bleeding marks that seep through legal parchment. Water-based inks are standard for regular self-inking units, whereas pre-inked gel stamps require specialized oil-based fluid formulated specifically for micro-porous material.
Replenishing your stamp is a simple maintenance task that requires only a few drops of fluid distributed evenly across the internal pad surface. Overfilling must be avoided, as excess fluid causes the fine borders and small lettering of your commission expiration date to pool into unreadable smudges. Allowing the re-inked pad to sit undisturbed for thirty minutes lets the pigment settle deeply into the cellular foam structure before stamping critical papers.
Keep your stamp in a secure, climate-controlled case away from direct sunlight, dust, and extreme temperature fluctuations. Under administrative regulations in every state, your stamp must remain under your direct, exclusive physical custody at all times. Leaving your marking device in an unlocked desk drawer or allowing family members access violates statutory safekeeping mandates and invites identity fraud.
Keeping an Accurate Official Journal of Notarial Acts
Alongside your physical stamp, an official record journal represents your primary evidentiary shield against fraud allegations and legal challenges. In many states, maintaining a sequential journal of all notarial acts is legally mandatory, while in remaining jurisdictions it stands as the recognized standard of professional practice. A well-kept journal chronicles the date, time, type of act, title of document, fee charged, and the method used to identify the signer.
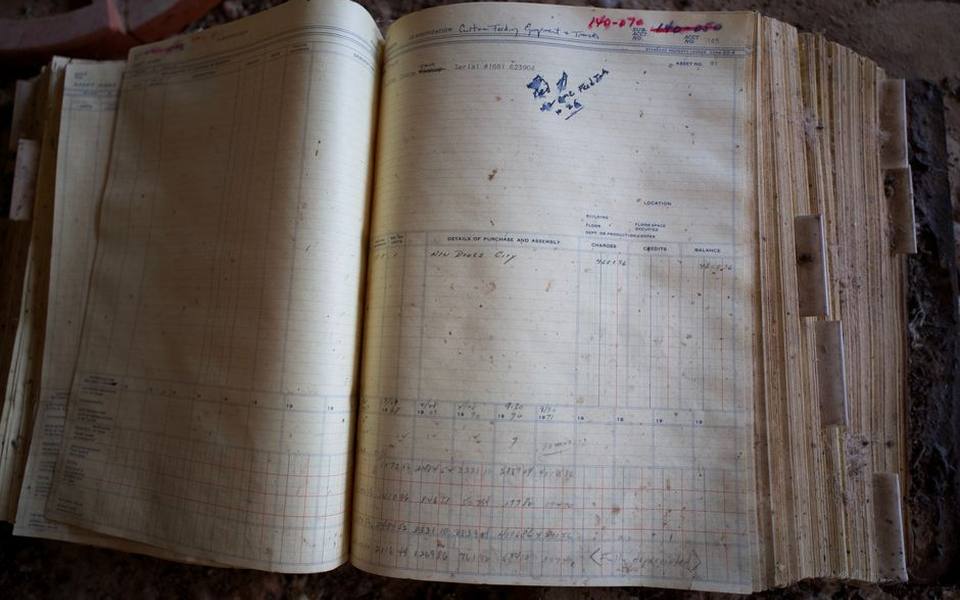
The most critical entry inside your journal is the method of identity verification and the signer's original physical signature. When examining state-issued photo credentials, you must record the issuing agency, serial number, and expiration date without writing down sensitive personal information like social security numbers. In situations where credible identifying witnesses vouch for an individual, their sworn statements, signatures, and addresses must also be inscribed directly within your sequential entries.
Tangible, bound journals with numbered pages prevent pages from being removed or inserted after the fact, maintaining chronological integrity in judicial disputes. Some states also permit or mandate the capture of a right thumbprint for specific high-value transactions involving real property transfers or general powers of attorney. Treat your completed journals as confidential archives, storing them in a locked safe alongside your current seal.
Understanding Surety Bonds vs Errors and Omissions Insurance
A common point of confusion among new practitioners involves the legal difference between a state-required surety bond and voluntary errors omissions insurance. In roughly thirty states, applicants must purchase a commercial surety bond, typically ranging from one thousand to twenty-five thousand dollars, before their commission becomes active. However, this bond does not protect the notary; it protects the public against financial loss caused by your intentional misconduct or negligence.
If an aggrieved client files a valid claim against your statutory surety bond, the commercial surety company pays the damages up to the bond limit, but then turns around and demands full financial reimbursement directly from you. If you make an innocent mistake on an acknowledgment certificate or fail to properly date a jurat, a standard bond leaves your personal bank accounts, vehicles, and real estate exposed to collection actions and costly lawsuits.
By contrast, purchasing dedicated eo insurance provides true personal indemnity coverage that defends your personal assets against claims of unintentional mistakes. If a title company, lender, or private signer files a lawsuit alleging that an improper notarization disrupted a multi-million-dollar closing, your errors and omissions policy pays for your legal defense counsel and covers any settled damages up to your policy limit.
How Much E&O Coverage You Actually Need
Determining the right coverage limit for your errors omissions insurance depends primarily on the volume and monetary scale of the documents you handle. Basic state surety packages often bundle a nominal five-thousand or ten-thousand-dollar liability policy for a low initial premium. While this modest amount might suffice for an office receptionist performing occasional single-page verifications, it proves dangerously inadequate for mobile practitioners dealing with real estate transfers or corporate resolutions.
Professionals who handle mortgage closings, estate planning documents, and commercial finance packages typically maintain policies of one hundred thousand dollars or more. In fact, most mortgage lenders, escrow companies, and title agencies require independent signing contractors to carry active twenty-five-thousand to one-hundred-thousand-dollar policies simply to be approved on their vendor panels. The annual premium for such coverage remains modest compared to the immense protection it affords.
When shopping for coverage, look for policies that include legal defense costs outside the stated indemnity policy limits. Legal battles involving contested signatures, contested wills, or property disputes often consume thousands of dollars in attorney retainers before a judge ever rules on the merits. A policy that covers specialized litigation defense ensures that an unfounded claim does not drain your operating capital.
Branching Into Specialized Practice and Mobile Work
Once your baseline commission, bond, stamp, and insurance are secured, you can expand beyond traditional counter service into lucrative specialty niches. One of the most popular paths involves working as loan signing agents who guide borrowers through extensive mortgage refinancing, purchase, and equity line document packages. These specialized assignments demand rigorous attention to detail, strict appointment punctuality, and complete familiarity with escrow settlement statements.
Another expanding frontier is the delivery of remote online notarization services using secure audio-video technology and digital tamper-evident seals. Many states now permit commissioned notaries to obtain supplemental remote endorsements, allowing them to verify signers across the country via knowledge-based authentication and credential analysis. This tech-forward approach removes geographic travel constraints while requiring specialized digital signature certificates and electronic journals.
International documentation creates another steady revenue stream through specialized authentication and apostille service coordination for individuals moving, studying, or conducting business abroad. Verifying documents intended for foreign governments requires flawless notarizations, as Secretary of State authentication departments reject any paperwork featuring stamp smudges or certificate discrepancies. Diversifying your service offerings allows you to build a resilient, full-time independent practice.
Setting Up Your Practice for Long-Term Compliance
Sustaining a reputable notarial career requires keeping meticulous track of your commission cycles and statutory updates. Notary commissions generally run for fixed terms, typically four or five years depending on your state, after which you must renew your credentials through your commissioning office. Letting your commission lapse even by a single day renders any subsequent notarizations legally invalid, exposing you to personal liability and administrative fines.
Keep your state commissioning agency informed whenever you change your legal name, residential address, or primary business location. Most state administrative rules mandate written notification within ten to thirty days of any relocation. Failing to report address changes can prevent you from receiving vital statutory renewal notices, regulatory rule amendments, or official state inquiries regarding past transactions.
Finally, join professional educational forums and routinely review updated state handbooks to stay current on evolving identity laws and notarial language. Certificate wording frequently changes when state legislatures update uniform acknowledgment acts. By coupling rigorous compliance with top-grade supplies and comprehensive insurance coverage, you establish a trusted professional foundation that protects both your clients and your career.
Published 2026-09-20 · reviewed with each rebuild, last September 2026.
Find notaries near you
The directory lists 5,516 notaries by state and city — pick your state or use the “Near me” button in the header.
More guides
-
 Service
A Practical Guide to Power of Attorney: What It Means, Typical Costs, and Proper Execution
-
 Service
Where and How to Get Fingerprinted for an FBI Background Check
-
 Owning
Understanding Real Estate Deeds: Transfer on Death, Deed of Trust, and Mortgages
-
 Service
What Is an Apostille? How to Get Birth Certificates and Documents Apostilled
-
 Service
Do Banks Notarize Documents? Free Branch Options, Notary Fees, and Licensing Guide
-
 Owning
Essential Legal Documents: Bills of Sale, Estate Affidavits, and Corporate Records
-
 Money
How Much Does a Notary Cost? Standard Fees, Travel Rates, and Extra Charges Explained
-
 Owning
Which Documents Need to Be Notarized? Leases, Notes, and Directives Explained
-
 Buying
Complete Bill of Sale Guide: Vehicle, Boat, and General Templates
-
 Service
Form I-9 Employment Eligibility Verification: Acceptable Documents and Rules
-
 Service
LLC Formation Documents, Residence Proof Affidavits, and Legal Verification
-
 Service
Fingerprinting and Live Scan Background Checks: Methods, Locations, and Cards
-
 Service
A Consumer Guide to Notary Public Services and Remote Online Notarization
-
 Service
Estate Planning Essentials: Wills, Codicils, and Healthcare Power of Attorney
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
Live Scan Fingerprinting and FBI Background Check Services Guide
-
 Service
Form I-9 Employment Verification and Identity Proofing Guide
-
 Service
Notary Training, Commissioning, Bonding, and E&O Insurance Guide
-
 Owning
A Complete Guide to Power of Attorney: Types, Forms, and Execution
-
 Money
Home Refinance and Cash-Out Mortgage Guide: Loan Closing, Rates, and Calculations
-
 Buying
Vehicle Title Transfer and Bill of Sale Guide: DMV Process, Forms, and Notarization
-
 Owning
Estate Planning and Real Estate Document Guide: Wills, Deeds, and Affidavits
-
 Owning
Articles of Incorporation and Corporate Filing Guide: LLCs, Nonprofits, and Bylaws
-
 Buying
Essential Notary Supplies Guide: Stamps, Embossing Seals, Journals, and Scanners
-
 Service
Remote Online Notarization and Mobile Notary Services Guide: How It Works and Costs
-
 Safety
Minor Travel Consent and Passport Documentation Guide: Forms, Rules, and Notarization
-
 Service
International Document Apostille, USCIS Translation, and Legalization Guide
-
 Money
Property Tax Appeal and Protest Guide: Process, Filing Forms, and Representation
-
 Buying
Motor Vehicle Bills of Sale and Title Transfers: A Complete Guide
-
 Money
A Practical Guide to 401(k) Hardship Withdrawals and Emergency Access
-
 Owning
Heavy-Duty Fasteners, Scanners, and Document Handling Equipment for Notaries
-
 Service
Live Scan Fingerprinting, Background Checks, and Identity Verification: A Complete Practical Guide
-
 Service
Notary Public Training, Essential Supplies, and Digital Workflow Guide
-
 Owning
Corporate Formation and Governance: Articles of Incorporation and Board Minutes
-
 Buying
Vehicle Bill of Sale and Title Transfer Notarization Guide
-
 Service
A Practical Guide to Affidavits, Proof of Residency, and Identity Declarations
-
 Money
Mortgage Cash-Out Refinancing: Equity Rules, Liens, and Closing Procedures
-
 Service
Certified Translation Services and State Department Legalization
-
 Service
A Practical Guide to Fingerprinting Services, LiveScan, and Identity Verification